Bottom Line Up Front: Across 50 major forecasts audited over the past 24 months (November 2024 – November 2026), BG2 Pod (87.5% strict hit rate) and Prof G / Prof G Markets (81.8% strict hit rate) sharply outperformed Pivot (50.0%) and the All-In Podcast (40.0%). The dividing line is clear: disciplined capital-allocation and sector-rotation frameworks beat dramatic political and macro-GDP hot takes.
1. Cross-Podcast Comparison Scorecard (2025–2026)
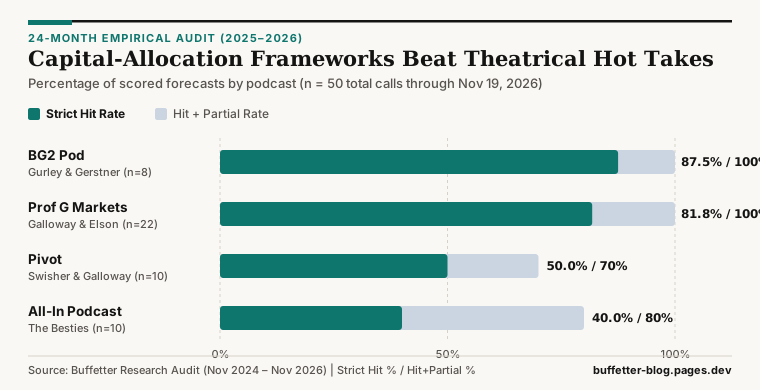
| Podcast | Hosts | Calls Scored | Hit | Partial | Miss | Strict Hit Rate | Hit + Partial | Core Strength | Primary Blind Spot |
|---|---|---|---|---|---|---|---|---|---|
| BG2 Pod | Bill Gurley & Brad Gerstner | 8 | 7 | 1 | 0 | 87.5% | 100.0% | Cost of capital, AI inference/CapEx math, SaaS disruption | Few wildcard or political binary bets |
| Prof G / Prof G Markets | Scott Galloway & Ed Elson | 22 | 18 | 4 | 0 | 81.8% | 100.0% | Sector rotations (EEM, nuclear, space, Waymo, prediction markets) |
Exact M&A structure (Musk/WBD) |
| Pivot | Kara Swisher & Scott Galloway | 10 | 5 | 2 | 3 | 50.0% | 70.0% | Tech-politics friction (Trump-Musk), AI duopoly pressure | Binary timing calls (2026 bailout, Vance presidency, Shein 2025 IPO) |
| All-In Podcast | Chamath, Calacanis, Sacks, Friedberg | 10 | 4 | 4 | 2 | 40.0% | 80.0% | Stablecoins, prediction markets, legacy SaaS compression | Over-optimistic GDP forecasts & wildcard mergers |
Grading Rubric: HIT = Clearly played out as predicted; PARTIAL = Directionally right or one half of a two-part call landed; MISS = Did not occur, missed the target year, or moved the opposite way.
2. BG2 Pod Breakdown (Bill Gurley & Brad Gerstner) — 87.5% Strict Hit Rate
Because Gurley (Benchmark) and Gerstner (Altimeter) deploy institutional capital, their 2025–2026 calls focused on interest-rate thresholds, inference scaling, and CapEx-to-FCF math rather than political theater.
| Year | Top Prediction | Verdict | Outcome Through November 2026 |
|---|---|---|---|
| 2025 | 10-Year Treasury Yield Stays Below 5% (Gerstner’s bull-market anchor) | HIT | The 10-year yield traded in a 4.0%–4.6% band (averaging 4.29%) throughout 2025, supporting an ~18% SPY gain. |
| 2025 | Accelerated Compute & HBM Memory Bottlenecks | HIT | Hardware and HBM supply constraints drove massive 2025 infrastructure monetization ahead of late-2026 valuation repricing. |
| 2025 | Shift to Inference-Time Compute & Reasoning Models | HIT | Frontier labs pivoted decisively from brute-force pre-training to chain-of-thought reasoning and agentic protocols. |
| 2025 | DOGE / Federal Spending & Regulatory Shakeup | PARTIAL | Deregulation and crypto/AI policy shifted meaningfully (e.g., GENIUS Act), though federal deficits and yield pressures persisted. |
| 2026 | Application Software Disruption (“Why do I need Excel?”) | HIT | Coding and workflow agents triggered a broad 2026 enterprise software multiple compression. |
| 2026 | Hyperscaler CapEx vs. Revenue Reality Check | HIT | Multi-trillion-dollar gaps between hyperscaler CapEx (e.g., GOOGL projecting $195B–$205B) and AI software revenue sparked the late-2026 infrastructure sell-off. |
| 2026 | IPO Market Thaw (Mega-cap listings like SpaceX) | HIT | 2026 delivered landmark listings including SpaceX (SPCX), Shein (00625.HK), and Anthropic’s late-2026 IPO push. |
| 2026 | Macro “Bogeyman”: Rates & Deficit Pressures Return | HIT | Long-term yields tested and surpassed 5% in late 2026 alongside hawkish Fed signals, pressuring high-multiple tech and commodities. |
3. Prof G / Prof G Markets Breakdown (Scott Galloway & Ed Elson) — 81.8% Strict Hit Rate
Galloway’s No Mercy / No Malice and Prof G Markets slates excelled at identifying underappreciated sector rotations and infrastructure bottlenecks, while Ed Elson added contrarian 2026 software value calls (ADBE, CRM, NOW, MSFT) during the SaaS sell-off.
| Year | Top Prediction | Verdict | Outcome Through November 2026 |
|---|---|---|---|
| 2025 | Emerging Markets Outperform U.S. Equities | HIT | EEM / MSCI EM returned +31%–34% in 2025, crushing SPY (+18%). |
| 2025 | Nuclear as Technology of the Year | HIT | Hyperscalers signed landmark nuclear PPAs (Microsoft/Constellation, Amazon/Talen, Google/NextEra, Meta/Vistra) and SMR deals. |
| 2025 | Power Couple: “OpenVidia” (NVDA + OpenAI) |
HIT | Dominated 2025 AI hardware and model mindshare before 2026 competitive/governance shocks. |
| 2025 | AI Company of 2025: META |
PARTIAL | META gained +12.7% in 2025 and shipped Llama 4, though OpenAI, Anthropic, and GOOGL captured frontier enterprise momentum. |
| 2025 | Musk Bids for WBD / CNN | PARTIAL | No direct buyout bid; instead, Musk invested ~$1B into Skydance as part of its $111B Paramount–WBD merger. |
| 2026 | AI Stocks Correct & Data Center Bubble Bursts | HIT | Late-2026 repricing hit NVDA, ORCL, and CoreWeave amid circular-financing scrutiny, Project Jupiter/Stargate delays, and Texas moratorium pushback. |
| 2026 | Nvidia & OpenAI Duopoly Under Siege | HIT | NVDA faced valuation compression and Jensen Huang’s resignation; OpenAI faced fierce competition from Anthropic and GOOGL. |
| 2026 | Space Becomes the Next Big “Thing” | HIT | SpaceX (SPCX) listed on Nasdaq at $1.5T–$1.75T, backed by Space Force/Starshield defense contracts. |
| 2026 | Waymo Speeds Ahead & Prediction Markets as Vice of the Year | HIT | Waymo topped 500k weekly paid rides across 14+ metros; Kalshi (~$40B) and Polymarket (~$20B) hit $44.8B peak monthly volume. |
| 2026 | Big Tech Stock Pick: AMZN |
PARTIAL | AMZN gained +11.6%–16.0% YTD through mid-Nov 2026, beating the Mag 7 average (+9.6%) and matching SPY (+11%–12.3%), though trailing AAPL (+26%–28%). |
(Note: All 22 Prof G items—10 in 2025 and 12 in 2026—score 18 Hits, 4 Partial, 0 Misses. See the companion Prof G & Pivot 24-Month Audit post for the full 22-item table.)
4. Pivot Podcast Breakdown (Kara Swisher & Scott Galloway) — 50.0% Strict Hit Rate
Pivot’s sharper misses came from dramatic binary headlines—exact IPO timing, a federal tech bailout, and a 2026 presidential succession—while its hits came from tech-political friction and AI competitive pressure.
| Year | Top Prediction | Verdict | Outcome Through November 2026 |
|---|---|---|---|
| 2025 | Trump 2.0 + Silicon Valley Alignment Turns Volatile (Trump-Musk Friction) | HIT | Tech CEOs oscillated between White House alignment and sharp public/policy clashes. |
| 2025 | Podcasting & Independent Media Milestone | HIT | Independent audio/video networks continued taking ad and political share from linear TV. |
| 2025 | Shein as 2025 IPO of the Year | MISS | Abandoned NY/London; delayed until Sept 1, 2026 in Hong Kong (00625.HK) at $26.3B–$26.5B (down from $100B). |
| 2026 | AI “Code Red” / Duopoly Pressured | HIT | Anthropic, GOOGL, and late-2026 valuation/governance shocks ended the unchallenged duopoly era. |
| 2026 | “The Next Bailout” (Federal tech/AI bailout in 2026) | MISS | AI/data center stocks corrected sharply, but no federal tech/AI bailout occurred in 2026. |
| 2026 | “President JD Vance?” (Ascending to the presidency in 2026) | MISS | Donald Trump remains President as of November 2026; JD Vance remains Vice President positioning for 2028. |
(Ep. 580 also featured six “Friend of Pivot” guests—Don Lemon, Anthony Scaramucci, Zoë Schiffer, Bill Cohan, Ian Bremmer, and Kyla Scanlon—whose individual 60-second calls are not publicly indexed verbatim.)
5. All-In Podcast Breakdown (Chamath, Calacanis, Sacks, Friedberg) — 40.0% Strict Hit Rate
Consistent with independent AI transcript audits placing All-In near a ~50% historical coin flip, the Besties nailed crypto/prediction-market infrastructure and SaaS compression, but missed on macro GDP hyper-bullishness and wildcard corporate mergers.
| Year | Top Prediction | Verdict | Outcome Through November 2026 |
|---|---|---|---|
| 2025 | Dollar-Denominated Stablecoins as Biggest Winner (Chamath) | HIT | The GENIUS Act was signed July 18, 2025; stablecoin market cap surged +49% ($205B to $306B). |
| 2025 | Robots & Autonomous Hardware (“Year of the Robot”) (Friedberg) | PARTIAL | Waymo scaled commercially, while humanoid robotics remained largely in factory R&D/hype mode. |
| 2025 | Nuclear Power & AI Energy Crunch | HIT | Hyperscaler nuclear PPAs and SMR partnerships surged across 2025. |
| 2025 | AI Agents Take Off Across Enterprise & Consumer | PARTIAL | Coding agents accelerated, while broad enterprise/consumer agentic workflows took until 2026 to mature. |
| 2025 | Big Businesses Integrating AI & GOOGL / TSLA Winners |
PARTIAL | GOOGL and AI adopters outperformed, while TSLA lagged Mag 7 peers in 2026. |
| 2026 | The End of Traditional SaaS (Chamath) | HIT | Legacy SaaS multiples compressed sharply in 2026 as AI workflow agents threatened seat-based models. |
| 2026 | Rise of Prediction Markets (Polymarket as News Gateway) | HIT | Prediction markets went mainstream across financial media and Google Finance at $44.8B peak monthly volume. |
| 2026 | Copper Bull Case (Chamath) | PARTIAL | Copper hit a record $6.85–$6.95/lb in Sept 2026 on AI data center demand before a late-2026 sell-off below $5.60–$5.70/lb erased YTD gains. |
| 2026 | “Trump Boom” 4.5%–6%+ U.S. GDP Growth | MISS | Actual 2026 real GDP tracked 2.2% (Q2) to 3.4% (Q3), well short of 4.5%–6%+ (after 2.3% in 2025). |
| 2026 | Wildcard: SpaceX Merges with TSLA Instead of Standalone IPO |
MISS | SpaceX completed a standalone Nasdaq IPO (SPCX) in 2026 at $1.5T–$1.75T. |
6. Key Takeaway for Investors
Across all four shows, predictive edge correlates inversely with theatricality:
- Follow Cost-of-Capital & Bottleneck Math (
BG2,Prof G): Tracking the 10-year Treasury yield, CapEx-to-FCF gaps, and physical bottlenecks (power, copper, HBM, orbital launch) produced 82%–88% hit rates. - Fade Binary Political & Macro Hyperbole (
Pivot,All-In): Calls for 6% GDP, federal tech bailouts, or same-year presidential transitions make great podcast clips—and consistently lose money.